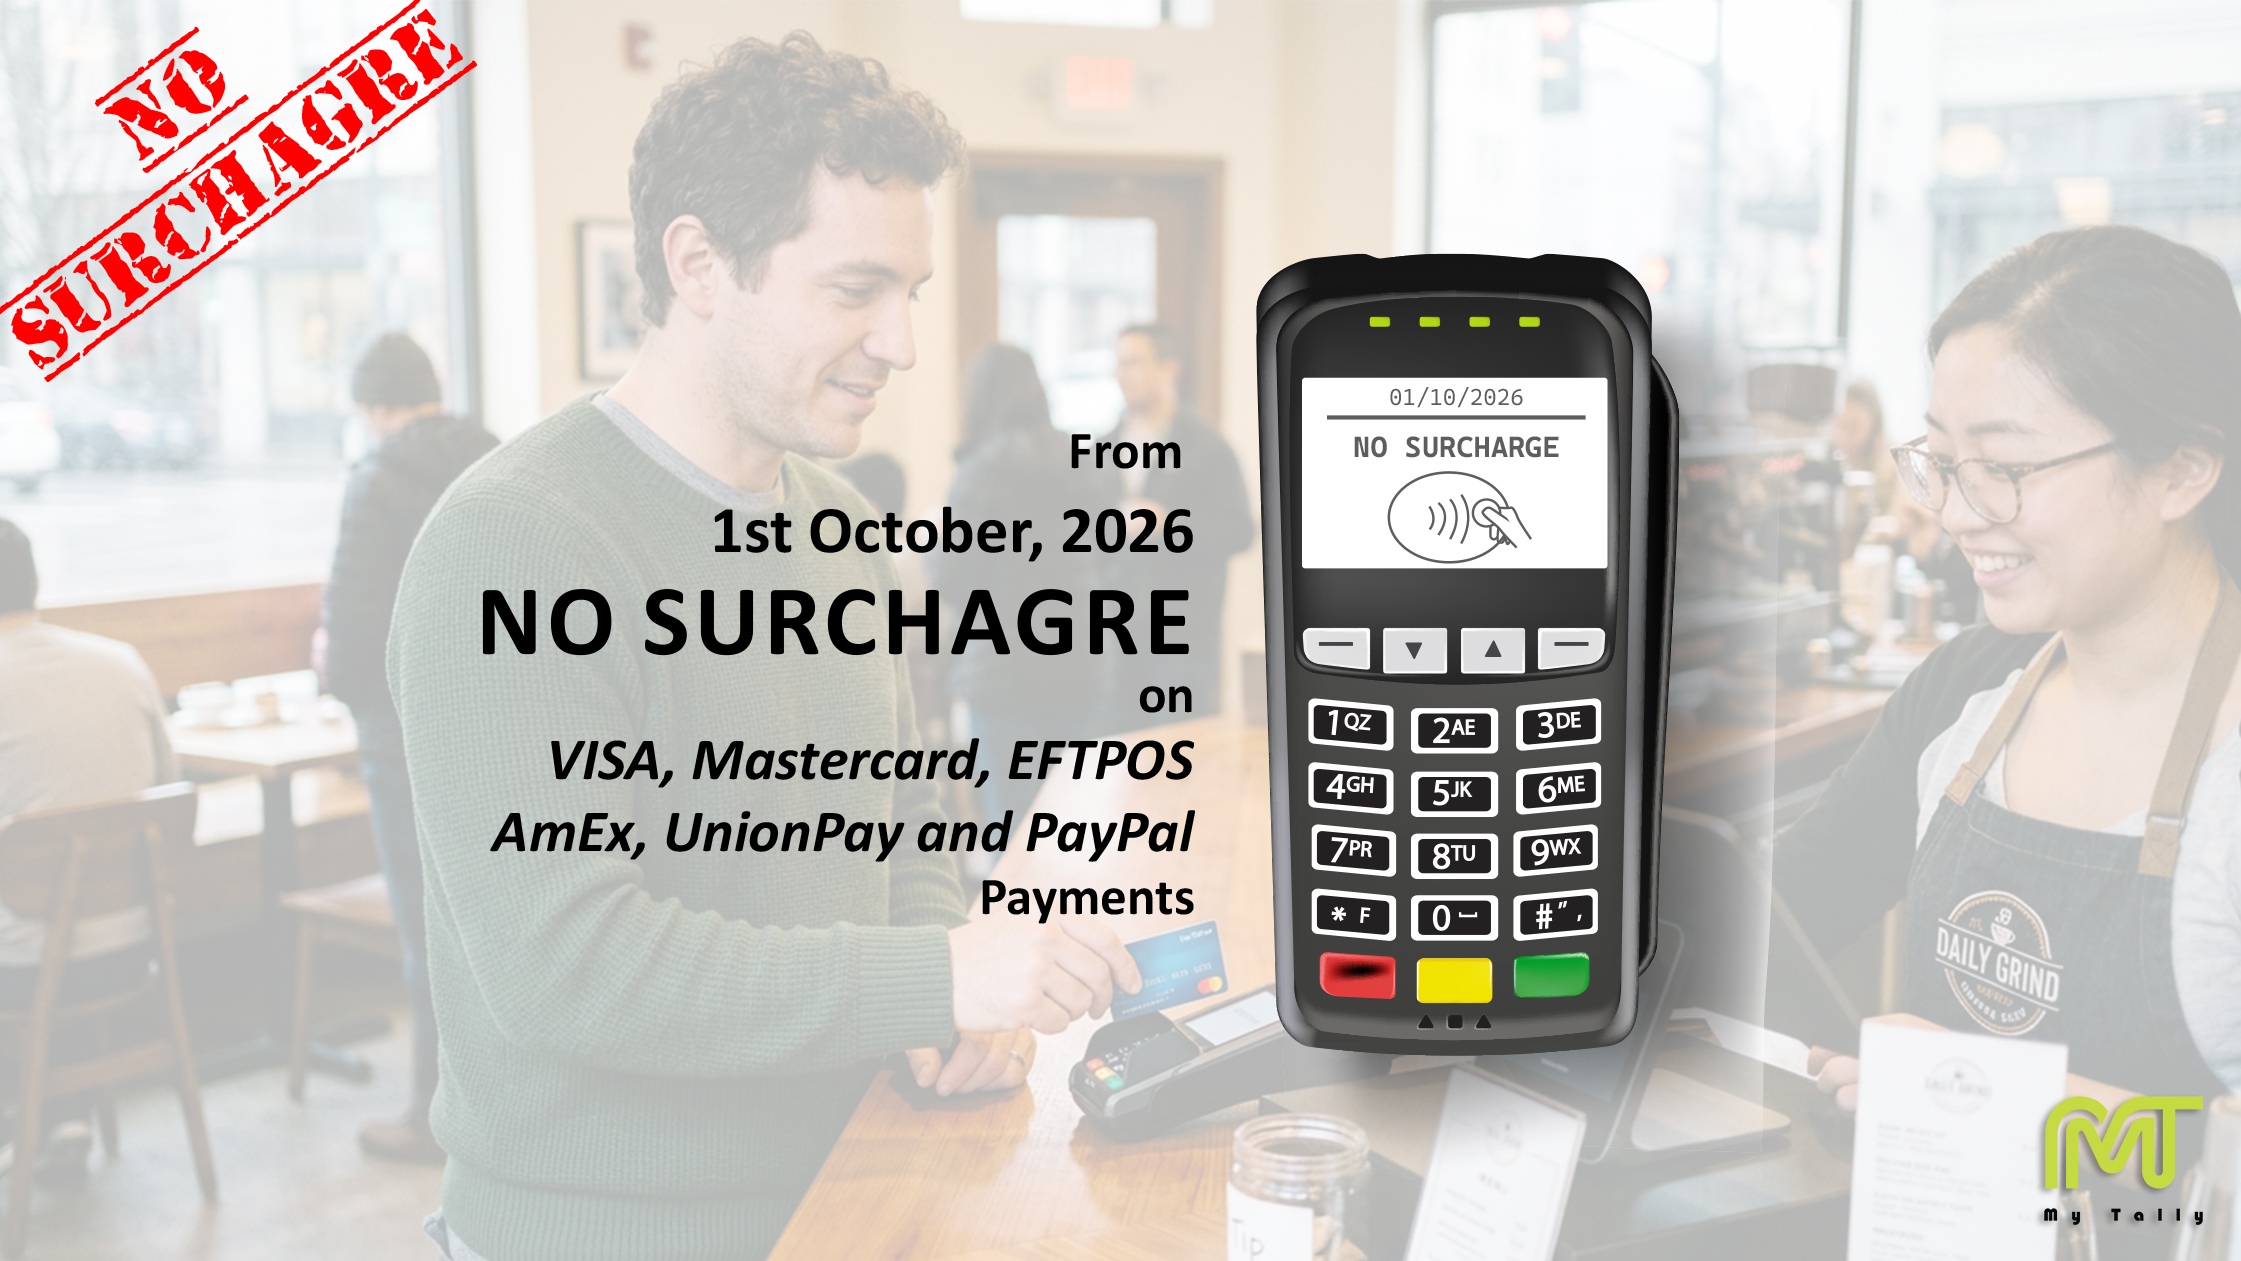
If you have ever tapped your card or phone for a $4 coffee only to see an extra 10 or 20 cents tacked onto the total, your receipts are about to get a lot simpler.
Starting 1 October 2026, Australia is officially banning card payment surcharges across major payment networks. Whether you are tapping a physical card, paying online, or using a digital wallet, the price you see will finally be the price you pay.
Here is a breakdown of what is changing, how it impacts your wallet, and what businesses need to know, backed by official policy and industry updates.
What Is Changing for Consumers?
Under new rules established by the Reserve Bank of Australia (RBA) and enforced by the Australian Competition and Consumer Commission (ACCC):
Zero Payment Surcharges: Merchants will no longer be permitted to add percentage-based or flat-rate surcharges for payments made via Visa, Mastercard, EFTPOS, American Express, UnionPay, or PayPal.
Upfront, Transparent Pricing: The advertised shelf price or online sticker price must be the final price paid at checkout.
**$1.6 Billion in Consumer Savings**_:_ As reported by The Guardian, the policy shift is projected to save Australian households approximately $1.6 billion annually in previously hidden checkout fees.
Note on Dining: This ban exempts weekend and public holiday surcharges in cafes and restaurants, as they relate to staff penalty rates rather than payment processing methods.
How It Works for Small Businesses & Terminals
To ensure small businesses aren't left holding the bill for transaction processing costs, the RBA has also slashed merchant interchange fee caps, reducing standard credit card fee caps to 0.3% (from 0.8%).
Payment hardware and accounting software providers are automating the transition:
Automatic Software Updates: Square Support and CommBank Newsroom have confirmed that payment terminals and point-of-sale systems will automatically turn off surcharge calculations on 1 October 2026.
Invoicing and E-Commerce: Xero Blog notes that online invoices integrated with Stripe or other payment gateways will automatically update so clients can pay by card without an added transaction fee.
What About Credit Card Rewards?
While consumers gain fee-free transactions, card issuers are adjusting to the reduced transaction fee revenue. According to financial analysis from The Guardian and CommBank, major banks and card providers are reviewing reward structures- which may lead to point caps or reduced complimentary perks (like travel insurance) on high-tier rewards cards.
Sources: Reserve Bank of Australia (RBA), Australian Competition and Consumer Commission (ACCC), The Guardian, CommBank Newsroom, Square Support, Xero Blog.